Business & Markets · · Team LATENT
Anthropic's retracted IPO terms and its amended S-1: a third quarter back in the red and $895.4 billion of compute commitments
On November 9, Anthropic sent banks IPO terms to raise up to $69.3 billion at $70 to $80 a share, then retracted them the same day as inaccurate. Its November 2 amended S-1 shows third-quarter revenue of $16.956 billion and an operating loss of $567 million. We calculate the valuation implied by the retracted range and the per-share value the filing implies for September 30, check LATENT's October 30 revenue estimate, break down $895.4 billion of commitments, and compare the seven placement buyers with what Anthropic pays them.
On the night of November 9, Anthropic's IPO terms reached its underwriting banks: 866.7 million shares at $70 to $80 each, raising up to $69.3 billion. A few hours later another email told the same banks the pricing information had been inaccurate. Reuters reported the sequence. The terms were pulled before they became a formal filing.
The terms are withdrawn, but the inputs to the price are already public. On November 2 Anthropic filed an amendment to its registration statement (S-1/A) that fills in the third-quarter figures and the total of its compute and other commitments, both blank in the October S-1. This article combines the retracted range with the S-1/A to calculate the valuation, the per-share value as of September 30, the third quarter's results and the makeup of the commitments. It also checks the third-quarter revenue LATENT back-calculated on October 30.
We checked the S-1/A figures in the SEC filing itself on November 10. The retracted terms are figures reported by Reuters, and Anthropic has called them inaccurate. Any calculation that uses them will change if the terms come back different. The valuations, per-share conversions and ratios are LATENT's calculations. This article does not recommend buying or selling any stock and does not forecast share prices.
Reuters: terms sent and retracted / Anthropic S-1/A
Key takeaways
- The retracted terms would have sold 866.7 million shares at $70 to $80, raising $60.7 billion to $69.3 billion. Anthropic says the pricing information was inaccurate. At that range the valuation would be about $1.2 trillion to $1.4 trillion. The S-1/A's values for the convertible notes and stock options put a share at about $70 on September 30, the bottom of the range.
- Third-quarter revenue was $16.956 billion; LATENT's October 30 estimate of about $16.6 billion was 2.1% below it. The quarter returned to an operating loss of $567 million, mainly because of $5.0 billion of compute bought under short-term commitments and a $2.0 billion charge for the donation matching program. Compute cost rose from 48% to 58% of revenue.
- Compute and other commitments total $895.4 billion, half of it leases that have not yet started. 24% carries termination rights or conditions before commencement. Of the seven companies said to be buying shares in a private placement, Google and Microsoft alone hold at least $166.2 billion of Anthropic's payment commitments, more than six times the $26 billion placement.
The retracted IPO terms
According to Reuters, the copy of the document sent to banks set out a sale of 866.7 million Class A shares: 843.3 million new shares from the company and 23.3 million from existing shareholders, at $70 to $80 a share. At the $80 top, proceeds would be $69.3 billion. Separately, it described a private placement in which seven companies, Alphabet, Nvidia, AMD, Broadcom, Micron, Microsoft and TSMC, would buy about $26 billion of Class N shares at the IPO price, closing right after the IPO.
A later email said the pricing information was inaccurate, and Anthropic said it would update the filing later. Reuters could not determine which figures were wrong. No SEC filing was withdrawn; some roundups that say the registration was withdrawn are wrong.
| Date (US) | Event |
|---|---|
| Oct 26 | S-1 made public, with share count, price range and Q3 revenue blank |
| Nov 2 | S-1/A filed with Q3 figures and total commitments; a securities registration statement filed in Japan |
| Nov 5 | Chip stocks and others plunge after the midterm results |
| Nov 6 | Bloomberg reports investors discussing a $1.2 trillion to $1.3 trillion valuation |
| Nov 9 | Terms sent to banks and retracted the same day |
| Nov 10 | Investor roadshow expected to start, per Reuters and Bloomberg |
The WSJ reported that Anthropic plans to set a valuation range this week and begin trading on Thursday or Friday of next week, which would be November 19 or 20. As of 16:13 Japan time on November 10, the SEC's filing list shows no S-1/A newer than November 2.
The S-1/A changed the following from the October 26 S-1. The price range and share count are still blank in the S-1/A.
| Item | S-1 (Oct 26) | S-1/A (Nov 2) |
|---|---|---|
| Q3 revenue and results | Blank | Revenue $16.956B, operating loss $567M |
| Total compute and other commitments | Blank | About $895.4B |
| Google commitment | At least about $114.5B | At least about $121.3B |
| Microsoft commitment term | Through May 2033 | Through June 2033 |
| Price range, share count | Blank | Blank |
Reuters: terms sent and retracted / TechCrunch on the WSJ report / SEC: Anthropic's filing list
Price per common share and the September 30 value
The $70 to $80 range is easier to place next to earlier funding prices. In the S-1/A, the 853.39 million preferred shares outstanding convert into 8,558.87 million common shares. One preferred share is about 10 common shares, so dividing a preferred price by 10 gives the price per common share.
Series G-1 in January and February 2026 was $259.14 per preferred share, or $25.91 per common share. Series H-1 in May and June was $589.01, or $58.90. Over about three and a half months from Series G to Series H, the price per share rose 2.27 times. The retracted range is 1.19 to 1.36 times the Series H price.
Two figures inside the S-1/A let us back out a per-share value for September 30. One is the fair value of the convertible notes: $130.502 billion at September 30. The only notes in the filing's convertible notes table are Amazon's two. The notes convert into 1.840 billion shares, which works out to about $70.9 a share. The other is stock options: 1.774 billion options outstanding with an intrinsic value of $119.103 billion and a weighted-average exercise price of $2.91. Intrinsic value per share plus the exercise price comes to about $70.0.
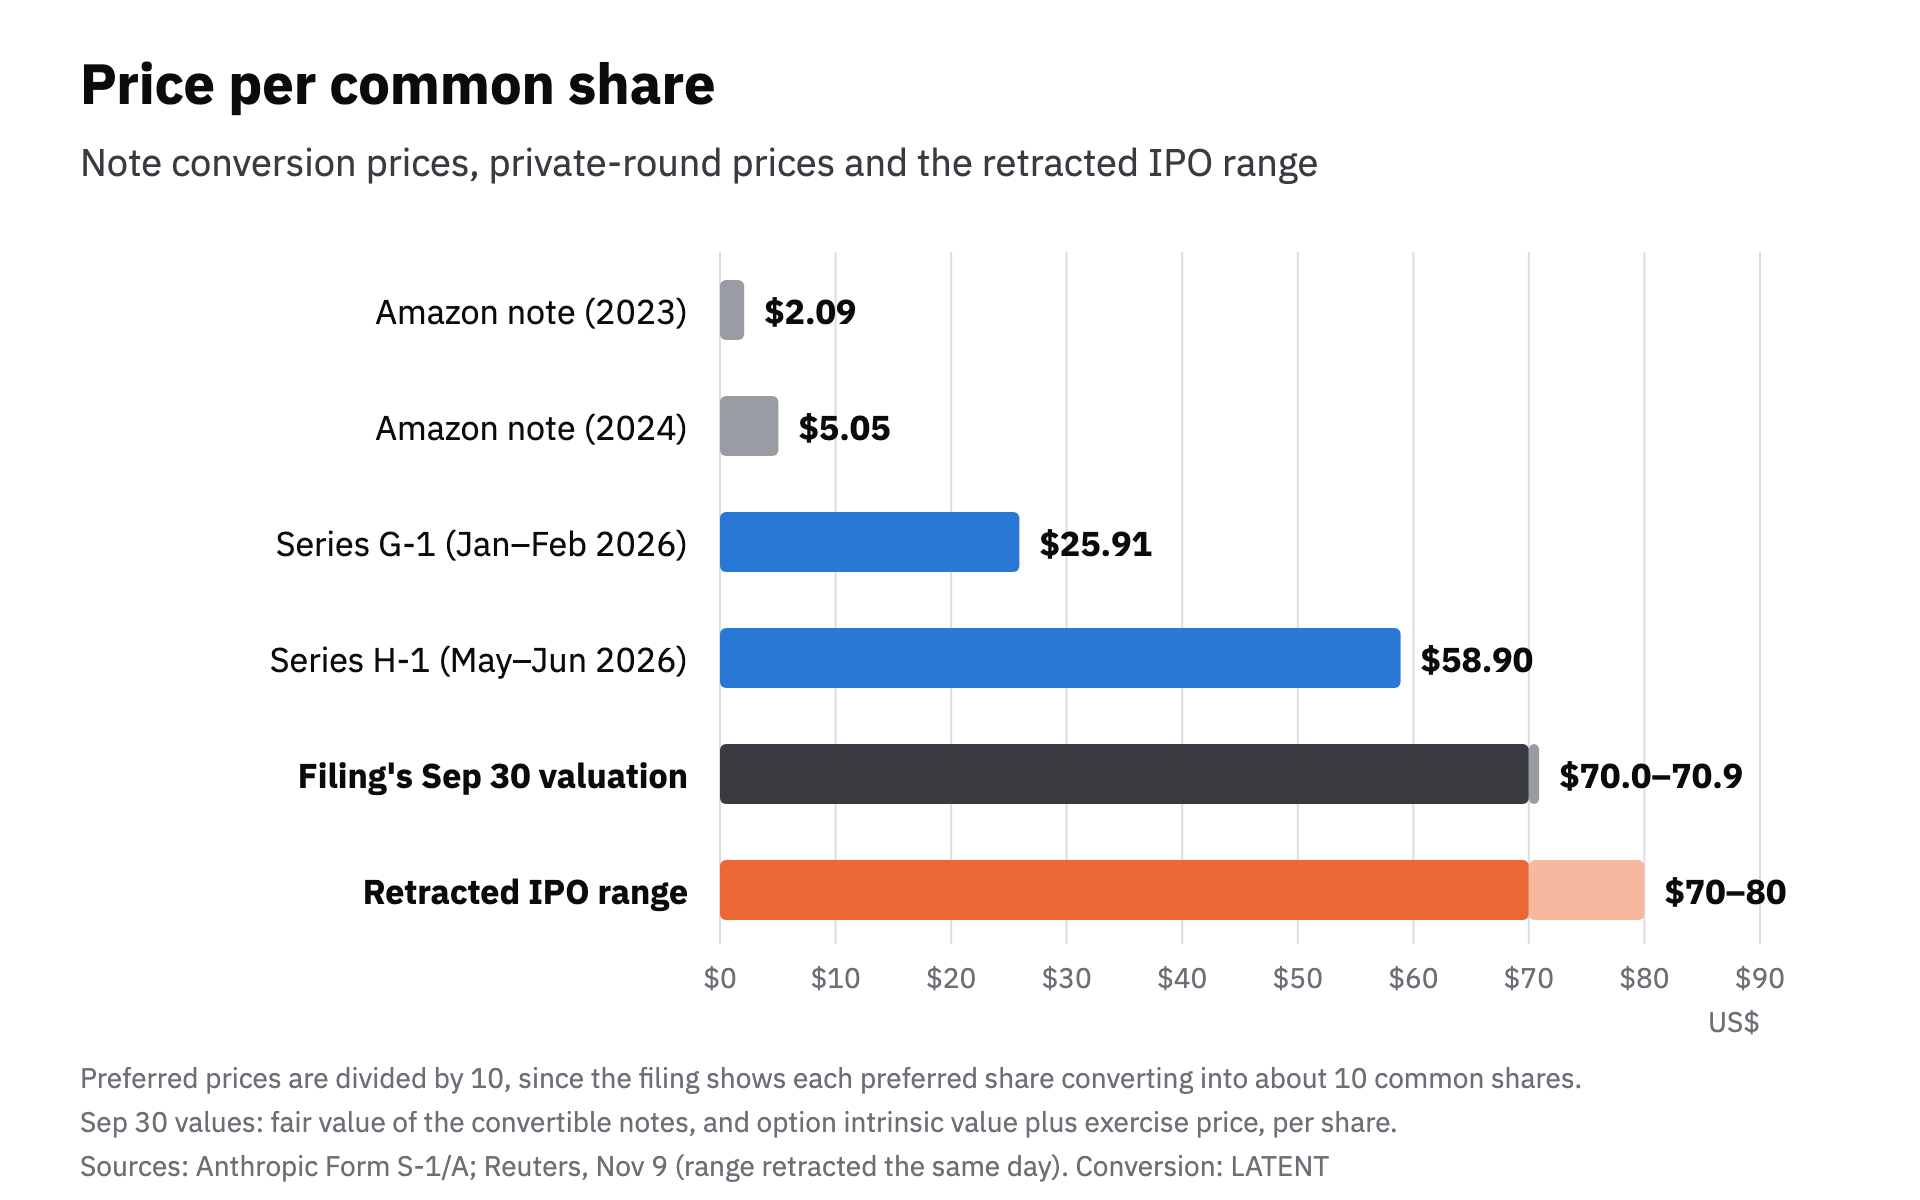
Both values are about $70, the bottom of the retracted range. The same calculation at December 31, 2025 gives about $17.7 from the options and about $20.4 from the notes. The per-share value implied by the filing rose about 3.5 to 4 times in nine months. The $80 top is about 14% above the September 30 value.
Anthropic S-1/A: capitalization table, convertible notes and stock compensation notes
The valuation implied by the retracted range
What would the valuation be at the retracted range? We calculated it two ways.
The first adds up the shares in the S-1/A. Starting from 2.169 billion common shares at September 30 and adding the converted preferred, the converted Amazon notes, stock options, performance-based restricted stock units (RSUs) and others gives about 15.51 billion shares before the IPO. To that we add the 843.3 million new shares sold in the IPO and the shares in the $26 billion placement.
| Item | Shares |
|---|---|
| Common stock (Sep 30) | 2.169B |
| Preferred stock (as converted) | 8.559B |
| Amazon notes (as converted) | 1.840B |
| Stock options | 1.774B |
| Performance-based RSUs | 1.128B |
| Other (restricted stock, donation matching and others) | 0.043B |
| New shares sold in the IPO | 0.843B |
| Placement ($26B divided by price) | 0.325B to 0.371B |
| Total | About 16.68B to 16.73B |
At $70 that share count gives about $1.17 trillion, and at $80 about $1.34 trillion.
The second extends the Series H valuation. Anthropic announced a post-money valuation of $965 billion for Series H. Dividing by $58.90 gives about 16.38 billion shares, about 0.87 billion more than the pre-IPO count from the first method. The filing leaves contingently issuable shares and RSUs granted after September 30 out of its dilution table, and the gap is likely those shares. Scaling $965 billion by the price ratio and adding the new money from the IPO gives about $1.23 trillion at $70 and about $1.40 trillion at $80.
Together, the two methods put the retracted range at a valuation of about $1.2 trillion to $1.4 trillion. Reported valuation figures had been falling since the summer.
| Date (US) | Report | Valuation |
|---|---|---|
| Aug 13 | FT | Some investors expect $2 trillion or more |
| Sep 11 | Reuters | Up to $100 billion raised at about $2 trillion |
| Oct 27 | Reuters | About $1.5 trillion |
| Nov 5 | WSJ | About $1.5 trillion; some investors see it nearer $1 trillion |
| Nov 6 | Bloomberg | $1.2 trillion to $1.3 trillion; some buyers mention $1.1 trillion |
| Nov 10 (morning in Japan) | Nikkei | $1.4 trillion to $1.5 trillion (before the retraction was reported) |
The $1.2 trillion to $1.4 trillion from the retracted range is below the $1.5 trillion reported since late October and includes Bloomberg's November 6 figures.
| Point | Valuation | Last quarter's revenue x4 | Multiple | Annualized revenue announced by the company | Multiple |
|---|---|---|---|---|---|
| Series G (Feb 12) | $380B | $8.16B (Q4 2025) | About 47x | $14B | About 27x |
| Series H (May 28) | $965B | $18.92B (Q1 2026) | About 51x | Over $47B | About 21x or less |
| Retracted terms (Nov 9) | About $1.2T to $1.4T | $67.82B (Q3 2026) | About 18x to 21x | None | None |
The price per share is at most 1.36 times Series H, while revenue grew 3.58 times from the first quarter to the third. On the last quarter's revenue, the valuation at the retracted range is about 18 to 21 times revenue, less than half the roughly 51 times at Series H. The range has risen less than revenue. The company's announced annualized revenue uses a different basis from a quarter times four, so we put it in a separate column.
Anthropic: Series H / Anthropic: Series G / Bloomberg: November 6 valuation report / Nikkei: November 10
Compared with the largest IPOs
The retracted terms' $60.7 billion to $69.3 billion would rank behind only SpaceX's $75.0 billion in June 2026. SpaceX sold 555.56 million shares at $135 and raised $85.7 billion including the overallotment. It was valued at $1.77 trillion at the IPO price and closed its first day up 19%. Against the previous record, Saudi Aramco's $25.6 billion in 2019, Anthropic's terms are 2.4 to 2.7 times as large.
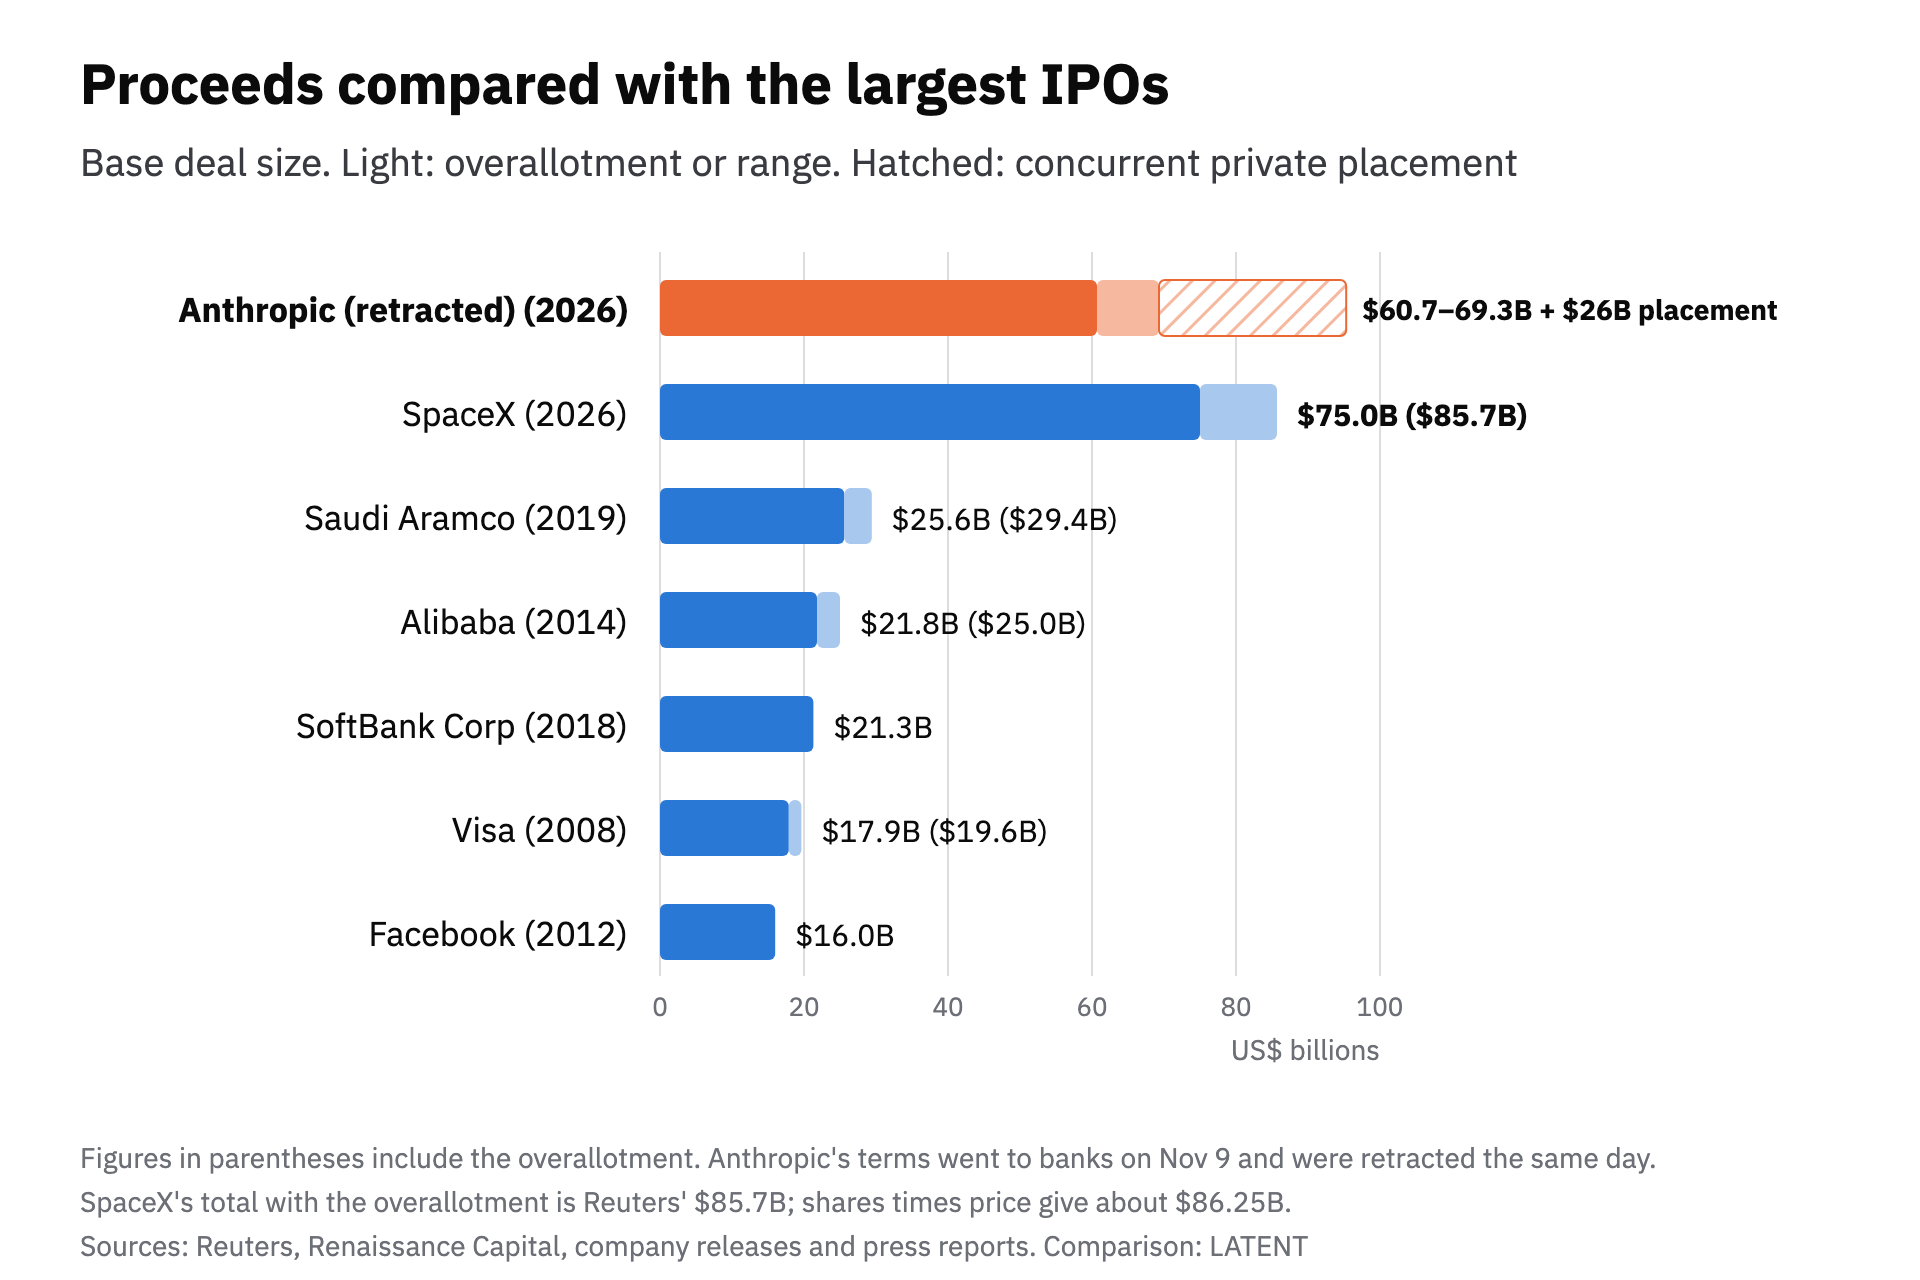
Adding the $26 billion placement, $86.7 billion to $95.3 billion would change hands at the IPO, more than SpaceX's total including the overallotment. The company would receive $59.0 billion to $67.5 billion from new shares plus the $26 billion placement, $85.0 billion to $93.5 billion in all. The $1.6 billion to $1.9 billion for the 23.3 million shares sold by existing holders would not go to the company.
| IPO | Year | Base proceeds | Including overallotment |
|---|---|---|---|
| SpaceX | 2026 | $75.0B | $85.7B |
| Anthropic (retracted terms) | 2026 | $60.7B to $69.3B | Not stated (separate $26B placement) |
| Saudi Aramco | 2019 | $25.6B | $29.4B |
| Alibaba | 2014 | $21.8B | About $25.0B |
| SoftBank Corp | 2018 | $21.3B | Not confirmed |
| Visa | 2008 | $17.9B | $19.65B |
| 2012 | $16.0B | Overallotment not exercised |
The dollar amount is among the largest ever, but the share of stock that would trade is small. The retracted terms' 866.7 million shares are about 5.2% of the roughly 16.7 billion shares counted in the valuation section. SpaceX's 555.56 million shares were about 4.2% of the roughly 13.1 billion shares implied by its IPO valuation. The rest is held by founders, employees, preferred investors, Amazon and others, and reaches the market as sale restrictions lapse. Amazon's 1.840 billion note shares alone are about 11% of the total.
Reuters: SpaceX overallotment / Renaissance Capital: largest IPOs
Third-quarter revenue and the October 30 estimate
The October 26 S-1 left revenue for the three months to September 30 blank. In our October 30 article, LATENT back-calculated that quarter at about $16.6 billion from revenue per employee and headcount, with a range of $16.3 billion to $17.5 billion as the assumptions moved. The S-1/A gives $16.956 billion.
| Item | Value |
|---|---|
| LATENT estimate (Oct 30) | About $16.6B (range $16.3B to $17.5B) |
| Investor figure reported by the FT | $16.8B |
| S-1/A actual | $16.956B |
| Gap | Estimate 2.1% below actual |
The actual figure fell inside the range, and the midpoint was about $0.36 billion low. Trailing 12-month revenue from the actuals is $35.282 billion; divided by about 5,300 employees that is about $6.66 million each. The October 30 calculation multiplied by $6.6 million for the filing's "more than $6.6 million," which is why it came out low.
The actuals also show growth slowing. Revenue rose 2.44 times from the first quarter to the second, but 1.47 times from the second to the third. Against the same quarter a year earlier it is 12.3 times, which the filing describes as growth of 1,127%. The filing also says price reductions with new model versions and contractual discounts cut revenue by about $600 million from the second quarter to the third, 3.5% of third-quarter revenue. The comparable effect from the third to the fourth quarter of 2025 was about $70 million.
Customers paying $100,000 or more a year passed 11,900, more than 12 times the 950-plus a year earlier. More than 1,900 pay $1 million or more and about 250 pay $10 million or more.
Related: What Anthropic's S-1 reveals about its operating profit / S-1/A quarterly results
A third quarter back in the red
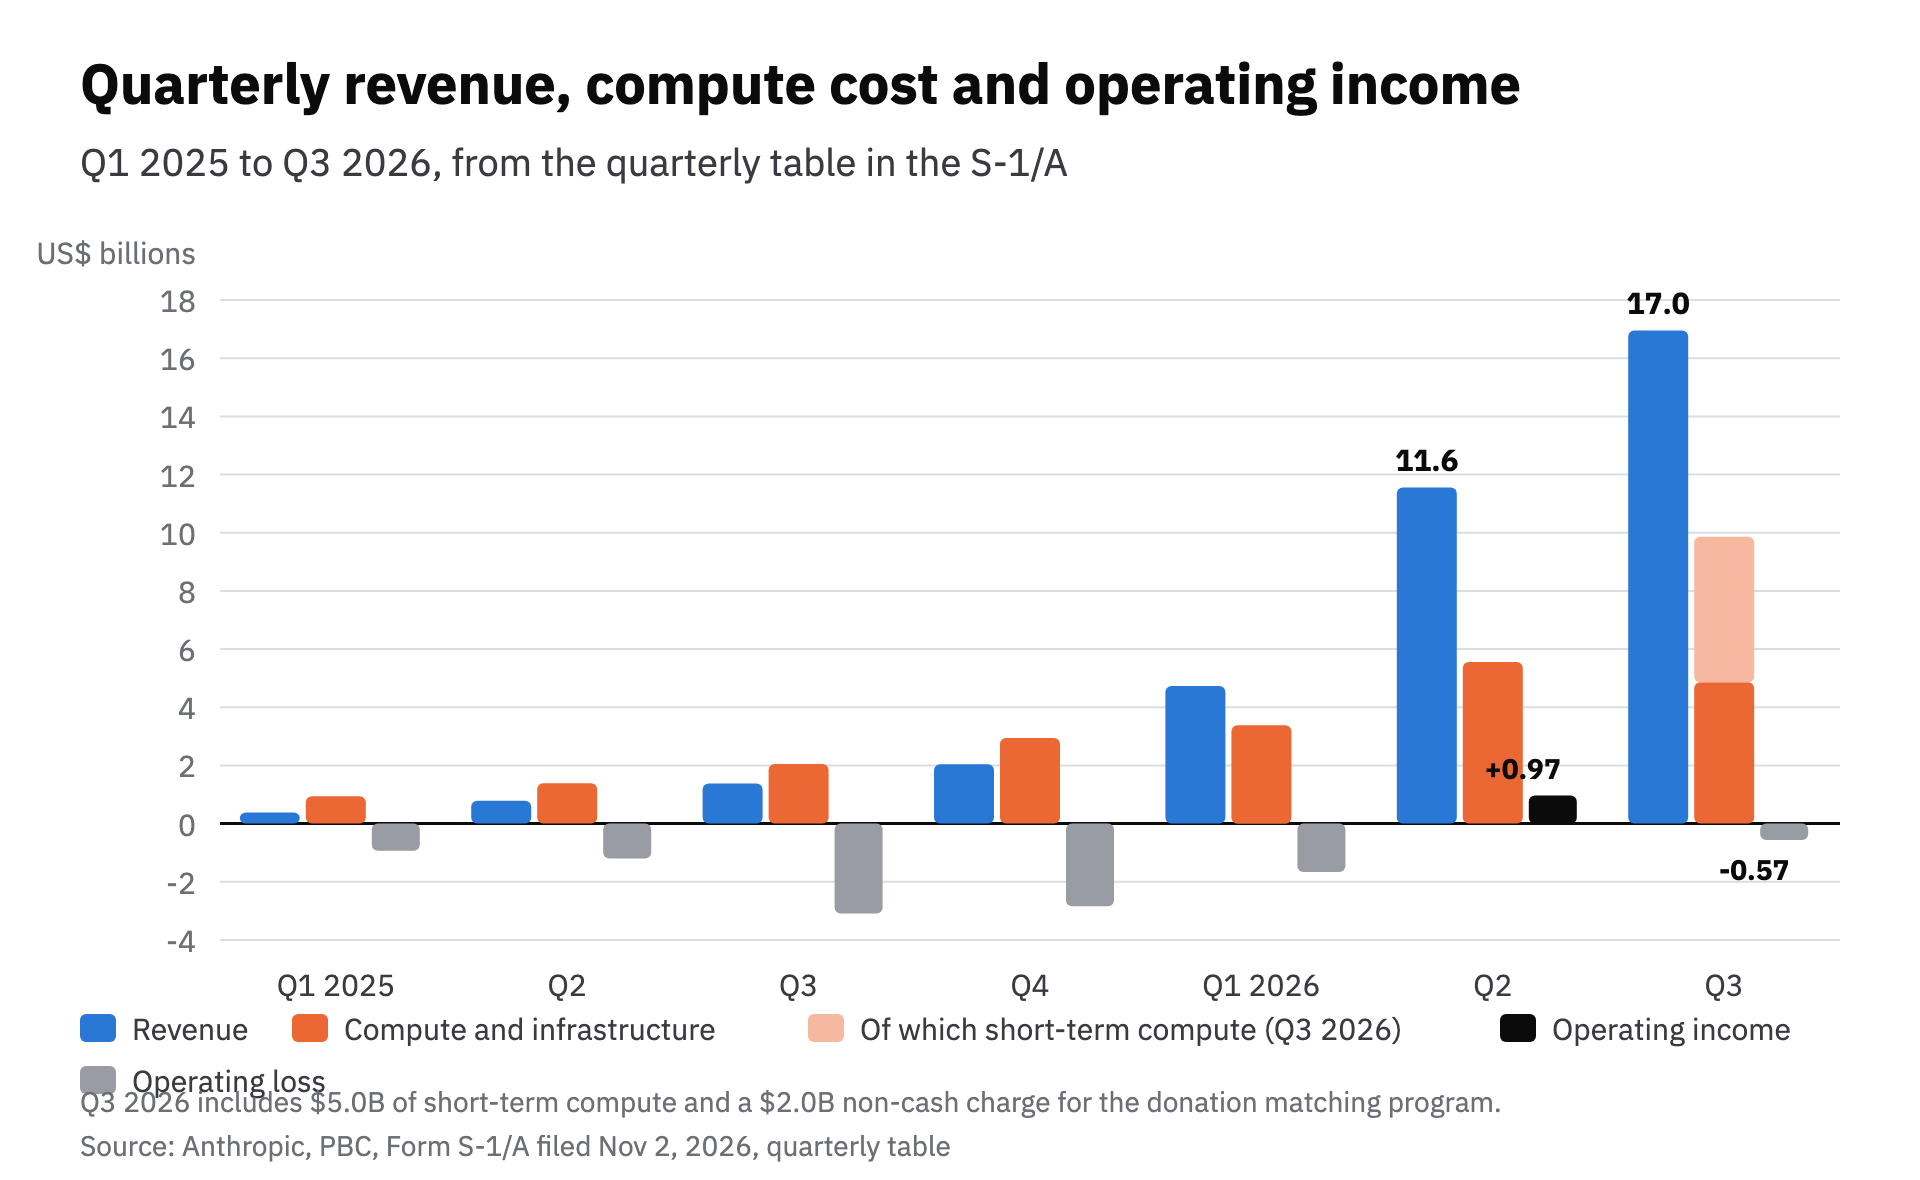
The second quarter, the only profitable one in the S-1, had operating income of $974 million. The third quarter had an operating loss of $567 million, so the profit lasted one quarter. Compute cost as a share of revenue fell from 251% in the first quarter of 2025 to 48% in the second quarter of 2026, then rose to 58% in the third.
| Quarter | Revenue | Compute cost | Ratio | Operating income |
|---|---|---|---|---|
| Q3 2025 | $1.382B | $2.047B | 148% | -$3.089B |
| Q4 2025 | $2.040B | $2.945B | 144% | -$2.836B |
| Q1 2026 | $4.731B | $3.387B | 72% | -$1.667B |
| Q2 2026 | $11.555B | $5.558B | 48% | $0.974B |
| Q3 2026 | $16.956B | $9.863B | 58% | -$0.567B |
The filing gives two main reasons for the loss. One is $5.0 billion of compute procured under short-term commitments, which it says costs "significantly more" than comparable compute bought under multi-year commitments. The other is a $2.0 billion charge for the donation matching program, under which the company matches with Class N shares when employees pledge part of their equity awards to charity. No cash goes out.
Separating the two: without the $2.0 billion donation matching charge, operating income would be $1.433 billion, 8.5% of revenue, nearly the same as the second quarter's 8.4%. Taking the $5.0 billion of short-term compute out of $9.863 billion leaves $4.863 billion, 29% of revenue and less than the second quarter's $5.558 billion of compute cost.
LATENT reads this as the cost of compute delivered under multi-year commitments not rising, with expensive short-term compute bought to keep up with demand. Anthropic buys compute 12 to 18 months before it can use it, so third-quarter usage growth would have outrun forecasts made more than a year earlier. But the second quarter's compute cost may also have included short-term compute, and the filing does not give that amount. This reading is unverified.
Other costs moved too. Here are the second and third quarters side by side.
| Expense | Q2 2026 | Q3 2026 | Change |
|---|---|---|---|
| Compute and infrastructure | $5.558B | $9.863B | +$4.305B |
| Personnel | $1.857B | $1.711B | -$0.146B |
| Sales, marketing and partnerships | $2.135B | $2.361B | +$0.226B |
| Other operating and administrative | $1.031B | $3.588B | +$2.557B |
| Total operating expenses | $10.581B | $17.523B | +$6.942B |
Of the $6.942 billion increase, compute accounts for 62% and other operating and administrative costs for 37%. $2.0 billion of the $2.557 billion rise in other costs is the donation matching charge. Personnel costs fell for the first time in the seven quarters shown, as stock compensation dropped when some option awards became fully vested. Sales and marketing was 14% of revenue, down from 22% in the first quarter; the filing attributes this to a lower share of revenue through channel partners and changed terms with them.
Outside operations, the $131.9 billion of cash and short-term investments at September 30 earned $1.248 billion of interest in the third quarter, more than twice the $567 million operating loss.
Adjusted operating income, as presented by the company, was $2.5 billion or 15% of revenue in the third quarter and $2.2 billion or 19% in the second. It excludes stock compensation and other items, and the margin fell by about the cost of the short-term compute. On cash, operating cash flow for the first nine months of 2026 was an inflow of $6.6 billion, up from an outflow of $2.0 billion a year earlier.
S-1/A quarterly table and management's discussion
Inside the $895.4 billion of commitments
The total of commitments, blank in the S-1, is filled in by the S-1/A: about $895.4 billion at September 30, which the filing says is "substantially all" related to compute and infrastructure. The total is the sum of five parts, and the parts add up to the filing's figure.
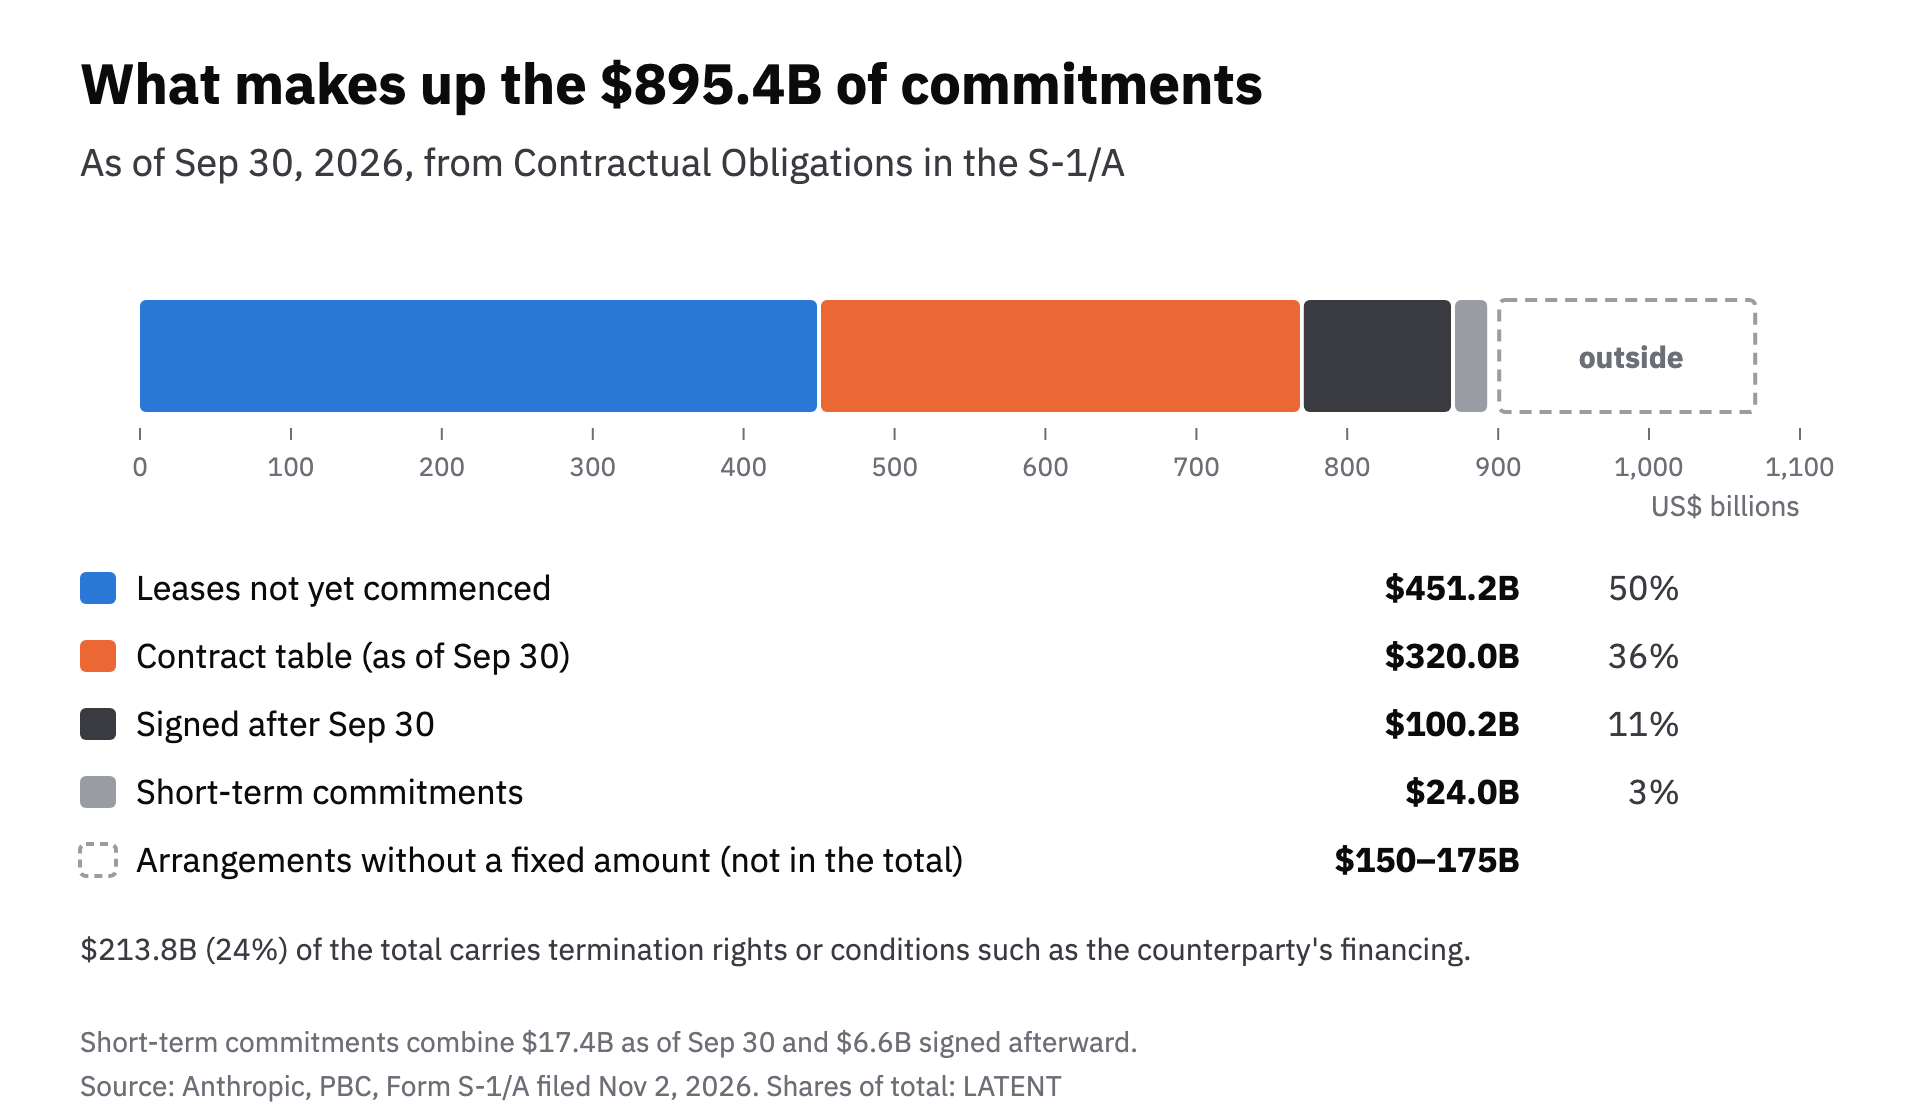
The largest part is $451.2 billion of leases signed but not yet commenced, half the total. Most start between 2026 and 2028, with an average term of about 10 years. Next comes $320.0 billion in the contract table as of September 30, then $100.2 billion signed after September 30.
Some arrangements are outside the total. The filing estimates the additional TPUs from Google, delivered between 2028 and 2031, at $125 billion to $150 billion, and says AMD Helios racks would exceed $20 billion in full. It estimates such arrangements without a fixed dollar amount at $150 billion to $175 billion in all. Adding them gives about $1.045 trillion to $1.070 trillion.
On the other hand, $213.8 billion (24%) of the total carries conditions before commencement or termination rights. If counterparties cannot secure financing, facilities or approvals, the arrangements can end. The filing does not break the $213.8 billion down by contract. In the individual descriptions, Nscale's up to about $44.6 billion depends on Nscale financing the GPUs and facilities within a set period, and SpaceXAI's up to $120.5 billion can be cancelled by either side on 90 days' notice once the initial periods end in January and March 2027.
| Counterparty | S-1/A amount | Term and conditions |
|---|---|---|
| At least about $121.3B | Apr 2026 to Jul 2033. About $114.5B in the S-1. Additional TPUs estimated separately at $125B to $150B | |
| Amazon | At least $110.0B | May 2026 to Apr 2036 |
| SpaceXAI | Up to $120.5B | Into 2029. About $3.1B a month from December. Initial non-cancelable periods end in Jan and Mar 2027 |
| Microsoft | At least $44.9B | Nov 2026 to Jun 2033 |
| Nscale | Up to about $44.6B | Into 2033. NVIDIA GPUs. Depends on Nscale's financing |
| AMD | Over $20B (outside the total) | First tranche of Helios racks in 2027 |
In the October 30 article, LATENT added up individual S-1 contracts to $676.1 billion to $701.1 billion, a figure that included Google's additional TPUs. On the same basis, the comparison is $551.1 billion without those TPUs against the S-1/A's $895.4 billion, a gap of $344.3 billion. The total includes leases not yet commenced and other items without individual amounts, and the filing does not let us split the gap further.
The timing of payments is also visible. About $69.8 billion is due in the 12 months from September 30, about $5.8 billion a month. In the contract table, annual payments rise to $29.2 billion in 2027, $44.4 billion in 2028 and $47.8 billion in 2029.
To compare scale with revenue: third-quarter revenue times four is about $67.8 billion a year, and the total commitments equal 13.2 years of it. Cash and short-term investments at September 30 were $131.9 billion, 1.9 times the next 12 months of payments. The IPO money would widen that margin.
S-1/A contractual obligations / Related: What Anthropic's S-1 reveals about its operating profit
Payments over the next 12 months and the revenue they need
The roughly $69.8 billion due in the 12 months from September 30 is about $5.8 billion a month. Third-quarter revenue averaged about $5.65 billion a month, so at current revenue the committed payments alone exceed a month's revenue. Third-quarter compute cost averaged about $3.29 billion a month, so the payments are 1.8 times that.
To gauge their weight against revenue, we applied the third quarter's ratio. Keeping $69.8 billion of payments at 58% of revenue would take about $120.3 billion a year, or about $30.1 billion a quarter, 1.77 times the third quarter. Keeping them at the second quarter's 48% would take about $36.4 billion a quarter, 2.14 times the third quarter.
The committed payments include office leases as well as compute, and payment timing does not match when costs are recognized, so this is a rough measure of scale. Even so, if the third quarter's 1.47-times growth continued, quarterly revenue would reach about $36.6 billion in two quarters. Whether current growth holds is what decides how heavy the commitments are.
S-1/A contractual obligations and quarterly table
The seven placement buyers and Anthropic's payments
The Class N shares in the placement carry the same economic rights as Class A shares but no votes except where the law requires. The S-1/A describes Class N holders as primarily strategic business partners. While the seven companies buy shares, Anthropic pays compute bills to them or to providers that use their products. Here are the amounts written in the S-1/A.
| Company | Relationship in the S-1/A |
|---|---|
| Alphabet (Google) | At least about $121.3B of compute commitments; additional TPUs estimated at $125B to $150B |
| Microsoft | At least $44.9B of compute commitments |
| Broadcom | Equipment lease from March 2026. Five-year rent of about $125.2B excluding interest; part assigned to financial partners |
| AMD | Helios racks; over $20B in full |
| Nvidia | SpaceXAI (up to $120.5B) and Nscale (up to about $44.6B) run on NVIDIA GPUs. No direct contract amount given |
| Micron | Named in the supply risk section as one of the main makers of high-bandwidth memory |
| TSMC | Named in the risk section as the company where advanced chip manufacturing is concentrated |
Google's and Microsoft's commitments alone come to at least $166.2 billion, 6.4 times the $26 billion placement. Adding the Broadcom lease gives $291.4 billion, more than 11 times. What the seven companies put in through the placement is a fraction of what Anthropic pays them. The S-1/A gives no direct contract amounts with Nvidia, Micron or TSMC.
The $26 billion placement appeared only in the retracted terms. The S-1/A names no placement buyers or amounts, and no report has given per-company amounts.
S-1/A: description of capital stock, contracts and risk factors / Related: Where the Money for AI Comes From
Amazon's convertible notes
Amazon is not among the seven placement buyers. It already holds Anthropic convertible notes, which convert into Class N shares at the IPO. According to the S-1/A, the outstanding principal is $2.186 billion under the 2023 agreement and $4.017 billion under the 2024 agreement, $6.203 billion in all. The conversion prices are $2.0928 and $5.0478 a share, for 1.840 billion shares in total. If the IPO price is lower, the notes convert at the lower price.
| Agreement | Principal | Conversion price | Shares | Value at $70 | Value at $80 |
|---|---|---|---|---|---|
| 2023 | $2.186B | $2.0928 | 1.045B | $73.1B | $83.6B |
| 2024 | $4.017B | $5.0478 | 0.796B | $55.7B | $63.7B |
| Total | $6.203B | None | 1.840B | $128.8B | $147.2B |
At $75, the middle of the retracted range, about $6.2 billion of principal becomes about $138 billion of stock, about 22 times. That increase already appears in Anthropic's income statement. The notes are carried at fair value, $130.502 billion at September 30. Their fair value rose $94.324 billion in the first nine months of 2026, 90% of the $104.039 billion net loss for the period. Most of the net loss is the rise in value of Amazon's notes, recorded as a liability of the company.
Amazon is subject to an ownership cap. Any amount above it converts quarterly after the IPO, or is repaid in cash if it cannot convert before maturity. Amazon will not necessarily receive everything at once at the IPO.
S-1/A: convertible notes and fair value notes
The offering in Japan
The S-1 includes Japan among the public offerings outside the United States. On November 2, Anthropic filed a securities registration statement with the Kanto Local Finance Bureau. According to Reuters, the offering in Japan is up to 552.9 billion yen, about $3.5 billion at 157.82 yen to the dollar. At $75, the middle of the retracted range, 552.9 billion yen is about 46.7 million shares, about 5.4% of the whole offering.
According to the Nikkei, this is the largest amount ever sold in Japan in an overseas company's IPO, about 60% more than SpaceX's roughly 347 billion yen in Japan. Mizuho Securities coordinates the domestic sale, with Goldman Sachs Securities, Mitsubishi UFJ Morgan Stanley Securities, Morgan Stanley MUFG Securities, Rakuten Securities and SBI Securities. Diamond ZAi reports that individuals can apply through SBI, Rakuten, Mizuho and Mitsubishi UFJ Morgan Stanley, but lottery and application periods have not been announced.
The 552.9 billion yen in the registration statement is a ceiling.
Reuters: the offering in Japan / Nikkei: size of the Japanese offering / Diamond ZAi: retail applications
What we will check next
Anthropic says it will update its filing. LATENT will check four things in the next one. First, the price range and share count: how far they move from the retracted $70 to $80 changes this article's valuation. Second, the placement: whether the S-1/A lists the $26 billion and the amount for each company. Third, the post-IPO share breakdown: whether the gap closes between this article's share count and the one implied by the Series H valuation. Fourth, fourth-quarter compute cost: with SpaceXAI's full capacity arriving in December at about $3.1 billion a month, whether short-term compute purchases continue will move the ratio.
Sources and scope
We checked the figures and text of the S-1/A and S-1 in the SEC filings themselves on November 10, 2026. We also checked the SEC's filing list at 16:13 Japan time on November 10 and found no amendment newer than November 2. That was before US trading opened on November 10; if an amendment follows, this article's range and valuation calculations will change. The retracted terms, the seven placement buyers and $26 billion, and the timing of the roadshow and first trade are reported figures that we could not check in a filing. The retracted terms come from a single Reuters report, and Anthropic declined to comment. Among valuation reports, Bloomberg's November 6 figures were checked in a podcast description. Past IPO sizes come from Reuters, Renaissance Capital, company announcements and press reports; we could not confirm SoftBank Corp's overallotment.
The size of the Japanese offering and the brokers come from Reuters and Nikkei articles; we did not read the registration statement itself. The brokers taking retail applications come from a Diamond ZAi article.
The conversions to common shares, the September 30 per-share value, the valuations, revenue multiples, shares of total commitments, and the comparison of the placement with payments are LATENT's calculations from figures in the filings and reports. The reading of third-quarter compute is LATENT's interpretation, which the filing does not state in a form we can verify.
- Anthropic, PBC, Form S-1/A (filed Nov 2)
- Anthropic, PBC, Form S-1 (filed Oct 26)
- Reuters, "Anthropic's nearly $70 billion IPO plan briefly circulated to banks, then retracted" (republished)
- Reuters Japanese edition on the retraction (republished)
- TechCrunch, "Anthropic reportedly plans to move forward with IPO plans"
- Bloomberg, The Tape, November 6 episode
- Nikkei (November 10)
- Anthropic: Series H
- Anthropic: Series G
- Reuters, "SpaceX IPO raises $85.7 billion" (republished)
- Renaissance Capital, Largest Global IPOs
- Reuters, "Anthropic plans to sell $3.5 billion of shares in Japan" (republished)
- Nikkei (November 2)
- Diamond ZAi article
- Related: What Anthropic's S-1 reveals about its operating profit
- Related: Where the Money for AI Comes From
- Related: Data center pause pledges after the US midterms and the chip selloff